The ESG margin discount is the smallest prize on offer.
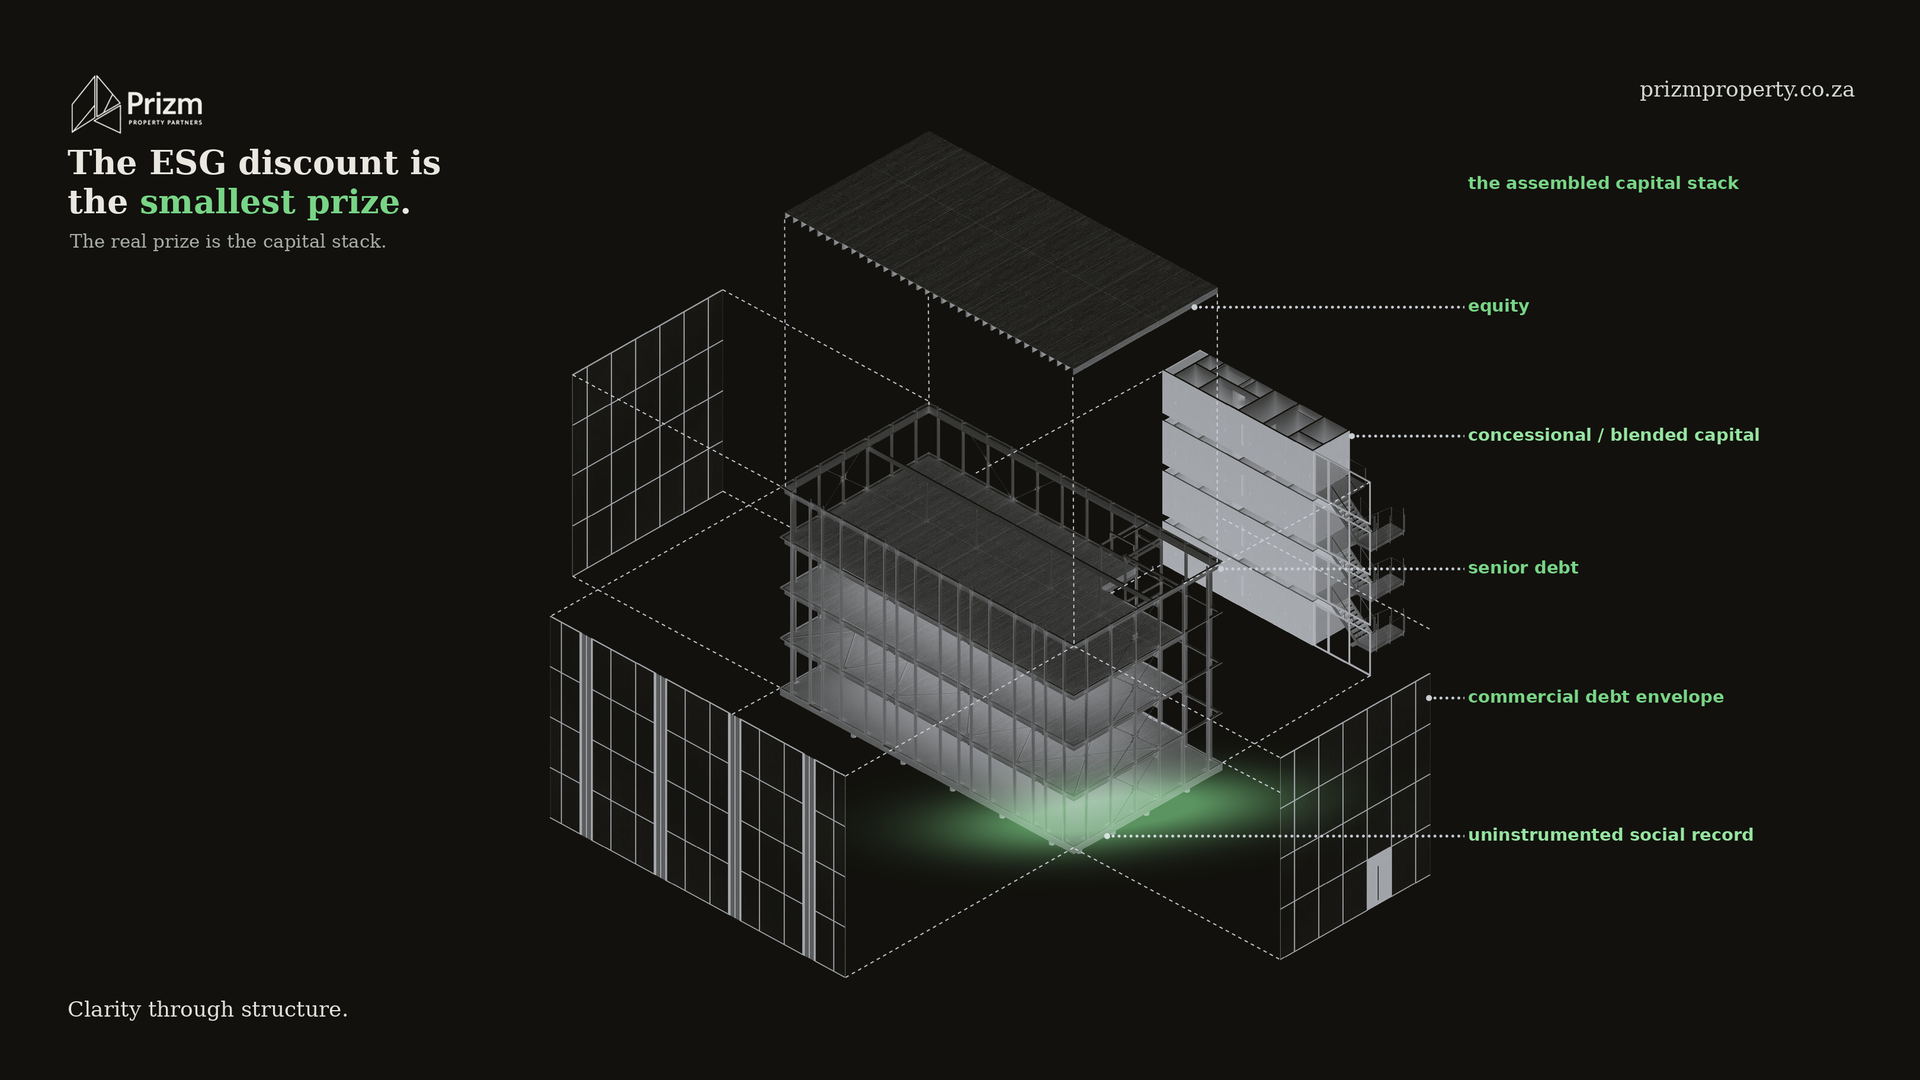
Take a well-run property business, the kind that shows up in portfolios across the country. It is conservatively geared, comfortably inside its covenants, and it funds itself the ordinary way, on senior bank debt at a competitive all-in rate. It also happens to do something socially useful. Its assets sit where they are needed, they sustain employment, and they widen access to services in places that had less of all three before it arrived. That is not why the business exists on paper, but it is a real and consistent feature of what it does.
Its cost of debt is keen, and it is worth asking why. Some of it is the low gearing and the track record. But part of it is simply that this is a business banks are comfortable lending to: stable, defensive, useful. That comfort is already sitting in the price. Nobody negotiated it into the loan. The bank quietly priced a borrower it trusts.
When the owner asks whether some of that margin can be captured explicitly, through an ESG linked structure, the honest first answer is that it can, a little, and it barely matters. A margin ratchet tied to a measurable environmental target might shave a few basis points off the labelled slice of the debt. Across the whole book that is a rounding error, the sort of figure one move in the repo rate wipes out before lunch. Worth taking if it is going. But if the ESG conversation ends at trimming the margin, it was not worth having.
That margin is the first of three ways ESG performance can move capital, and the smallest. The other two, access and structure, are where the value actually sits, and neither starts with price.
What matters is what the business builds next
Sooner or later it takes on a development with a component the bank isn't keen to fund on ordinary terms, a piece that carries real social value but presents an unfamiliar risk and a longer ramp, the sort of thing senior debt wasn't really intended to hold. Left to the commercial lender alone, that component slips. It becomes a later phase, then a maybe, then a line that gets value-engineered out the moment the budget tightens.
This is where the shape of the capital stack starts to matter far more than its price. There is a pool of development-finance and concessional capital designed to fund what commercial capital cannot or will not fund on ordinary terms. Bring a concessional or first-loss tranche into the stack and the numbers can shift: the tenor can lengthen, the equity requirement can fall, and the difficult component can become financeable rather than being dropped. That is not a few basis points. That is the difference between the scheme the owner designed and the scheme the bank would have allowed.
So why can't the owner simply reach for that capital? Because development-finance money doesn't lend against a good story. It lends against an evidenced one. To pull a concessional tranche into the stack, the business has to show, in numbers a credit committee will accept, what measurable social outputs and outcomes it actually produces, against a fixed baseline, with a method and a source someone can audit.
A business like this has usually been producing those outcomes for years, steadily, and has never recorded them in that form. They live in the annual report as narrative and in the cost of debt as an invisible discount. They do not exist as the baselined, verifiable evidence a development-finance lender can price. The performance is real; the evidence that would let capital reward it is missing. That gap, not the quality of the business, is the thing standing between the owner and the structural capital.
Where the value is hiding
And that shows where the value is hiding, which is not in the environmental story. Environmental performance is metered. Energy, water, carbon, certification, all of it is measurable, increasingly financed, and now carries a visible premium in the market data. That pillar already has an established measurement and financing infrastructure; the only real question left on it is how far to push. The uncaptured asset is the social record, and it is uncaptured precisely because it is the hardest thing to measure and therefore the thing almost nobody measures. The few deals that carry a social target usually reach for the safe corporate metrics, boardroom diversity and the like. Almost no one instruments developmental social outcomes in property. The business that does it first is not squeezing into a crowded market. There is barely a market there yet.
Governance sits in the same place. A conservatively run business that transacts at arm's length already has much of the governance infrastructure a development-finance lender treats as its price of entry. Today that gets discovered slowly, in diligence, as a box to be checked. Presented up front, as evidence, it becomes part of the case instead of a hurdle inside it.
The honest advice to a business of this kind is to stop shopping for a discount and start building the evidence. The margin saving is a rounding error. The real prize is a capital structure that can fund what the business is trying to build, and it turns entirely on whether the social and governance performance it already delivers can be measured to a standard someone will lend against.
The most valuable thing on the balance sheet is often the thing no valuer has counted: years of social output that was never written down in a form capital could read. Put it on paper properly and it stops being a paragraph in the annual report and becomes part of the funding.
The levers, and what they are worth
Underneath the argument sit three mechanisms, unequal in power.
- Pricing is the first: a sustainability-linked loan or bond that moves a margin against a performance target. The contractual adjustment is small, a median of about ten basis points across a large sample of loans, with reported ratchets running from roughly one to twenty-five. Whether that even translates into a genuinely cheaper loan is contested: of the studies that test the spread itself, most find no significant benefit at all. It is the lever everyone reaches for, and the weakest of the three.
- Access is the second: a green or social use-of-proceeds instrument that opens a pool of mandated capital otherwise closed to the raise, its spread advantage to be tested in the market rather than assumed.
- Structure is the third: development-finance and blended capital, concessional and first-loss tranches, guarantees, reshaping the stack itself. Pricing is bounded by the size of a margin. Structure is bounded only by the size of the tranche the evidence can unlock, which is why it dwarfs the rest.
Two numbers frame the opportunity. Over the decade to December 2025, green-certified prime and A-grade offices returned a 172-basis-point annual advantage against non-certified properties over the period; read it as a value premium, not evidence of a 172-basis-point cut in the cost of debt, and note it is only beginning to appear outside offices. And of the sustainability-linked loans and bonds issued worldwide, only about a fifth carry any social or governance target at all, most of those alongside an environmental one. The developmental social record almost nobody instruments is therefore one of the largest areas of unclaimed value in the market.
If you run or finance a business like this, the question is: what is your social record worth to your capital structure, and why is it still invisible?